
What Is Finance and Insurance (F&I)?
Finance and Insurance (F&I) is the dealership department that handles the financial side of a vehicle sale. Once a customer and salesperson agree on the vehicle and price, the F&I manager (sometimes called the business manager) arranges financing or a lease, completes the contracts and required disclosures, and offers optional protection products.
Common F&I products include vehicle service contracts (often called extended warranties), GAP coverage, tire and wheel protection, prepaid maintenance plans, appearance and paint protection, key replacement and theft deterrent products. Availability and rules differ by state.
Why F&I Matters
F&I is one of the most profitable areas of a dealership:
- It is a major gross profit source. Income from financing arrangements and product sales often makes up a large share of a dealership’s profit per vehicle, especially when front-end vehicle margins are thin.
- It is measured per vehicle. Dealers track F&I gross per retail unit, a key component of per vehicle retail (PVR) figures, along with product penetration rates.
- It shapes the customer experience. Long waits or high-pressure tactics in the F&I office are a common complaint in dealership reviews.
- It carries compliance risk. Lending, disclosure, fair lending and privacy rules apply, and errors can bring regulatory and legal consequences.
How F&I Works
A typical F&I process looks like this:
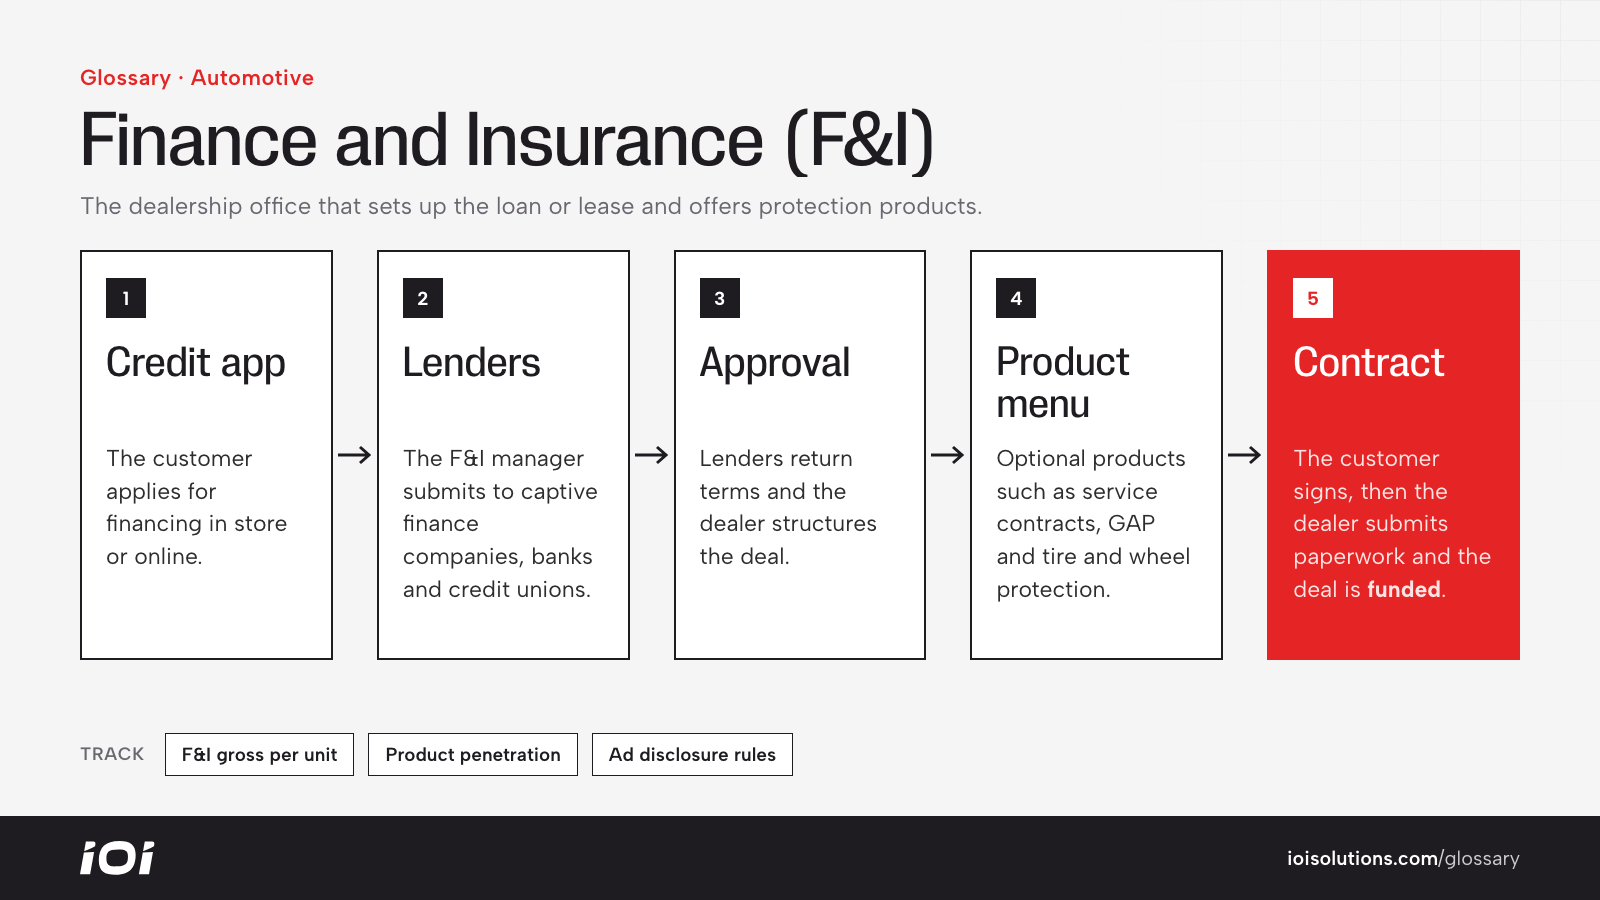
- Credit application: the customer applies, either in store or online.
- Lender submission: the F&I manager sends the application to one or more lenders, including captive finance companies, banks and credit unions.
- Approval and structure: lenders return approvals with terms. The dealer structures the deal, and in many cases may earn compensation from the lender for arranging the loan, within limits set by the lender and the law.
- Product presentation: the manager presents optional protection products, often using a menu that shows several package options.
- Contracting: the customer signs the retail installment contract or lease and any product agreements.
- Funding: the dealer submits paperwork to the lender and receives payment for the vehicle.
How F&I Affects Marketing
F&I influences what dealers can advertise and how shoppers buy:
- Finance advertising rules: mentioning certain credit terms, such as a monthly payment or down payment, can trigger federal disclosure requirements under the Truth in Lending Act (and the Consumer Leasing Act for leases), plus any state rules. Ads must include the required details clearly.
- Digital retailing: online tools let shoppers estimate payments, get pre-qualified and review protection products before arriving. Well-integrated digital retailing can generate highly qualified leads and shorten time in store.
- Credit-focused campaigns: dealers serving buyers with limited or damaged credit often run specific campaigns, which need careful, compliant messaging and must follow ad platform policies on financial services. See subprime auto lending.
- Reputation: transparency in F&I improves reviews and repeat business.
For example, a dealer that adds an online pre-qualification step to its vehicle pages can identify buyers who are ready to purchase and route them to sales with financing already in progress.
Best Practices
- Have compliance review finance ads before they run, including social and video content.
- Be transparent about optional products; customers should understand what they are buying and that it is optional.
- Connect online and in-store F&I so shoppers do not repeat steps they already completed.
- Track F&I results by lead source to see which marketing channels bring the most valuable buyers.
- Protect customer data collected in credit applications with strong security practices.